Production Pulls Back Slightly in October as Narrowbodies Hold Steady /// Widebody Inventories Normalize as Clearing Backlogs Spikes Lead Times /// Deliveries Soften in October Ahead of Anticipated Year-End Ramp Up
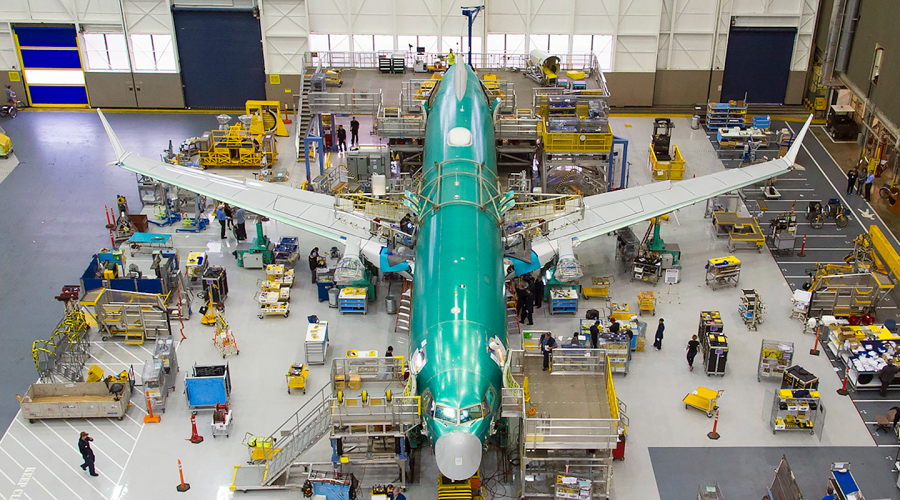
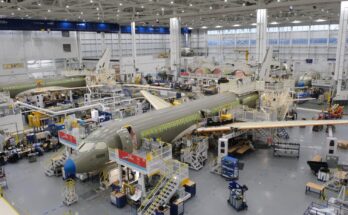
737 MAX FAL – Image – Defence News India
Production by Market Segment
The data in this summary is derived from our Commercial Aircraft OEM Intelligence Brief and only offers a broad overview of the commercial aircraft industry by market segment. For in-depth OEM- and program-specific analysis that incorporates these performance indicators to evaluate the health and execution of commercial aircraft manufacturers, explore the full Commercial Aircraft OEM Intelligence Brief.
Commercial aircraft manufacturing moderated slightly in October 2026, with total production slowing to 142 units from 146 in September, halting the sharp rebound seen at the end of the third quarter while remaining well ahead of August’s 131 units. The month-over-month decline was concentrated in widebody and regional assembly lines, whereas narrowbody production remained relatively the same, increasing marginally to 115 units from 113 in September and 105 in August. Widebody production slowed to 20 aircraft after climbing to 24 in September, falling back in line with the 20 units built in both July and August as widebody production lines continued to confront constraints. Within the smaller sectors, regional jet manufacturing contracted to three aircraft after an unusually active September saw seven units completed, while turboprop output doubled to four airframes from two the prior month. Through the first ten months of 2026, total commercial aircraft production increased to 1,283 aircraft. Narrowbodies continue to serve as the main driver of global manufacturing at 1,026 units year-to-date, followed by 198 widebodies, 35 regional jets, and 24 turboprops.
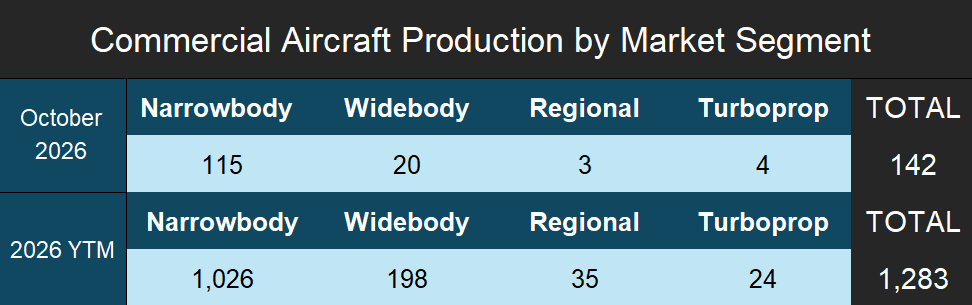
- Production data represents the actual number of aircraft produced in October 2026. Forecast International considers an aircraft produced upon its first flight. This may differ from an OEM’s definition of produced.
Inventories by Market Segment
Total commercial aircraft inventory climbed to 131% of combined monthly production target rates across all market segments as of October 31st, 2026. This increase was driven by the narrowbody sector, where inventory rose to 122% of production target rates from 108% in September, reversing recent progress as deliveries failed to show the typical seasonal uptick anticipated in the opening month of the fourth quarter. In contrast, widebody inventory dropped to 133% of current production targets, shedding 25 percentage points from September’s 158% reading as manufacturers drew down stored airframes. Rather than signaling a structural shift, this reduction marks a normalization toward healthier inventory levels following months of elevated levels of stored widebody aircraft. The smaller sectors continued to carry the highest relative inventory positions, with regional jets holding flat at 240% and turboprops remaining unchanged at 233% of their respective target rates. While these figures represent the highest levels of inventory on paper, the elevated percentages are largely a byproduct of modest monthly production rates, which disproportionately amplify the inventory ratios.
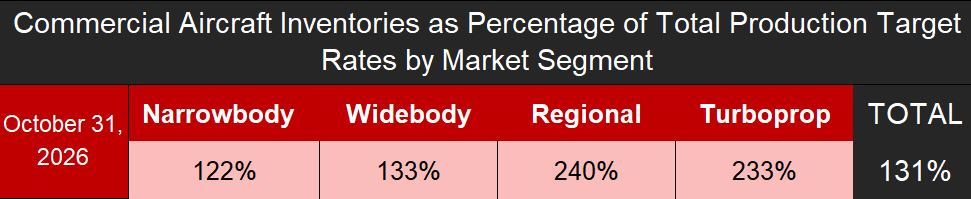
- Inventories represent the number of aircraft that have completed their first test flight but have not been delivered to the customer. Aircraft progressing through the final assembly line that have not completed their first test flight are not considered inventory.
Average Production-to-Delivery Lead Times
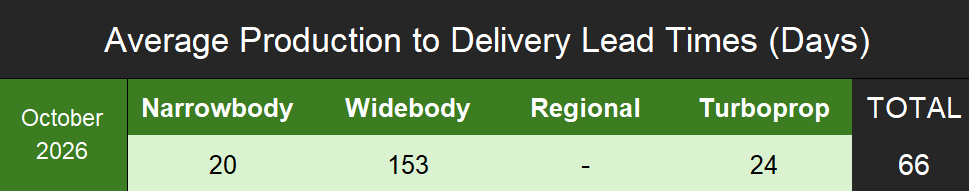
In October 2026, the overall average time from first flight to contractual delivery across all market segments reached 66 days, which reversed late-summer improvements and doubled the 33-day figure recorded in September. The sharp increase was driven entirely by the widebody segment, where the average days from production-to-delivery jumped to 153 days from just 28 days in September. This surge comes as no surprise given the substantial inventory drawdown observed in widebodies this month, as airlines finally accepted airframes that had been held up by persistent cabin seating delays. On the other hand, narrowbody lead times showed continued operational improvement, declining to 20 days compared to 25 in September and the 24 days recorded in both July and August. This progress is a positive sign for the year-end delivery ramp-up typical of manufacturers in the fourth quarter, demonstrating that newly produced aircraft are moving efficiently to customers, which should support higher delivery rates through the end of the year. Among the remaining categories, turboprop programs averaged 24 days from first flight to handover, down from 46 days in August and September, while no regional jet lead time could be calculated for the month due to a lack of paired first-flight and delivery events.
Projected Deliveries
Based on our commercial aircraft delivery tracking for October 2026, major global OEMs delivered an estimated 119 aircraft during the month, pulling back from the 142 units delivered in September and returning toward late-summer volumes. Airbus led total industry deliveries by matching its September total of 67 aircraft, anchored by 50 A320neo-family deliveries alongside seven A220s, six A350s, and four A330neos. Meanwhile, Boeing deliveries slipped to an estimated 49 aircraft from 56 in September, primarily due to softer 737 MAX output, which fell to 32 units from 43 the month prior. Boeing’s widebody deliveries expanded to 17 units, driven by 11 787 Dreamliners, four 767s, and two 777s, with higher 787 deliveries providing a meaningful offset to the MAX slowdown. Regional manufacturers also cooled off considerably, as Embraer delivered just two E195-E2s, ATR delivered a single ATR 72-600 after sending out four in September, and COMAC again posted zero deliveries across both its C909 and C919 programs.
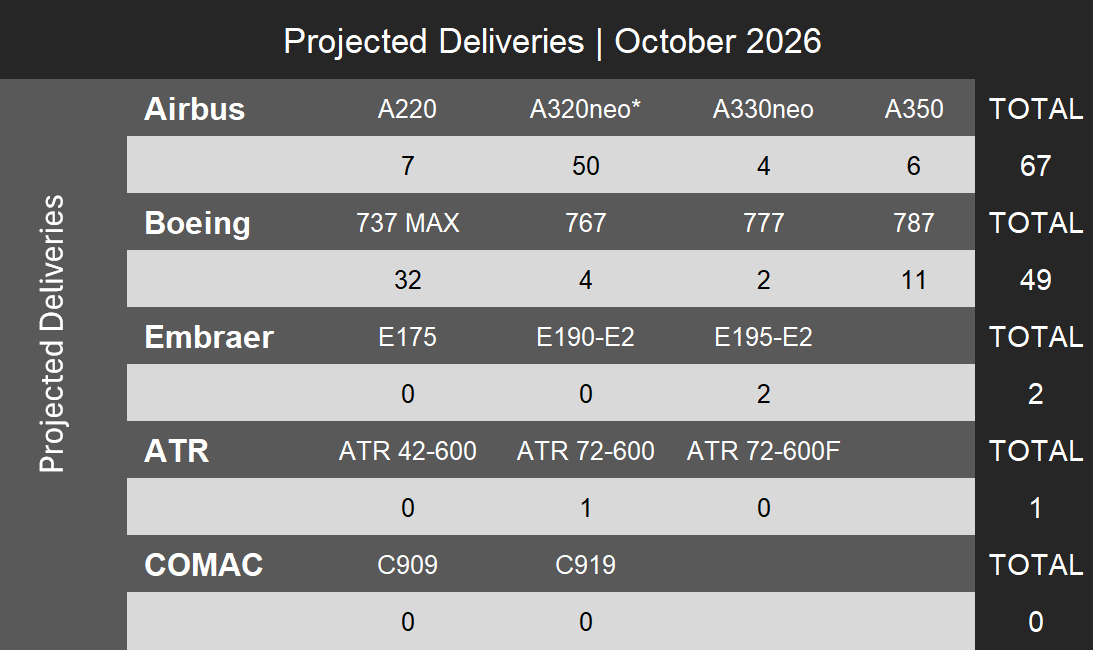
- Deliveries summary is based on Forecast International’s internal research. Numbers are not official and are not provided by the manufacturer.
- A320neo numbers include all variants for the family; A319neo, A320neo and A321neo
With diverse experience in the commercial aviation industry, Grant joins Forecast International as the Lead Analyst for Commercial Aerospace. He began his career at the Boeing Company, where he worked as a geospatial analyst, designing and building aeronautical navigation charts for Department of Defense flight operations.
Grant then joined a boutique global aviation consulting firm that focused on the aviation finance and leasing industry. In this role he conducted valuations and market analysis of commercial aircraft and engines for banks, private equity firms, lessors and airlines for the purposes of trading, collateralizing and securitizing commercial aviation assets.
Grant has a deep passion for the aviation industry and is also a pilot. He holds his Commercial Pilots License and Instrument Rating in addition to being a FAA Certified Flight Instructor.